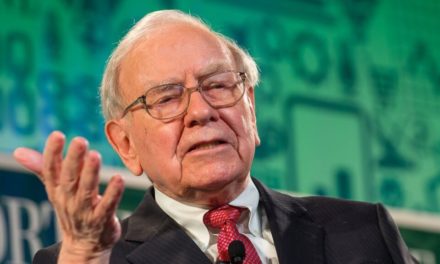

Stephen Schwarzman and the Next Phase of Private Markets
Stephen Schwarzman, chairman and chief executive of Blackstone, has increasingly positioned the firm around the investment opportunities created by artificial intelligence, particularly data centres, power infrastructure and private technology companies.
Blackstone’s assets reached $1.35 trillion in the second quarter of 2026, with the firm reporting strong gains from AI-related investments. Nine of its ten best-performing investments were linked to AI, according to Reuters. (Reuters)
The scale of the AI investment cycle raises an important question for private markets: how should investors deploy capital once an initial infrastructure boom has attracted enormous amounts of funding?
Schwarzman’s answer has increasingly focused on infrastructure, long-duration assets and opportunities that are difficult to replicate through public markets. Blackstone has described AI as a major structural investment theme, while also acknowledging concerns about excessive enthusiasm.
The next phase may therefore be less about simply gaining exposure to AI and more about identifying assets with durable demand, contracted revenues and attractive risk-adjusted returns.


“Nine of its ten best-performing investments were linked to AI, according to Reuters”
WEALTH TRAINING COMPANY
AI Infrastructure Creates New Private-Market Opportunities
AI is creating demand for a broad ecosystem of physical infrastructure. Data centres require electricity, cooling systems, networking equipment and specialised computing capacity.
Blackstone’s data centre platform has expanded significantly, with its total value reaching approximately $185 billion, including facilities under construction. The firm expects the platform could double over the next few years if its development pipeline progresses as planned. (MarketBeat)
Schwarzman has described the AI transformation as having substantial implications for industry and financial markets. In a recent earnings discussion, he said “We are in the early days of what I believe will be the most consequential transformation of industry and markets in a generation”.
The opportunity extends beyond owning data centres. Blackstone has also invested in power, utilities, AI companies and financing structures designed to support large-scale computing demand.

“We are in the early days of what I believe will be the most consequential transformation of industry and markets in a generation”
Stephen Schwarzman
For private-market investors, this creates opportunities to provide capital at several points in the AI infrastructure chain rather than relying exclusively on equity exposure to technology companies.
Valuations Become More Important as Capital Floods Into AI
Rapid investment growth can create attractive opportunities, but it can also make valuation discipline more important.
Private markets are particularly relevant because assets such as data centres and infrastructure projects are generally less liquid than publicly traded securities. Their valuations may not adjust as quickly when market expectations change.
S&P Global has highlighted concerns around AI infrastructure debt, noting that illiquid assets can lag public-market repricing and that apparently diversified portfolios may contain concentrated exposure to the same hyperscale technology companies. (S&P Global)
This makes underwriting particularly important.
Investors need to examine projected demand, customer concentration, financing structures, operating costs and the durability of contracted revenues.
The current AI cycle also creates a distinction between assets that benefit directly from rising computing demand and companies whose valuations depend primarily on expectations of future technological breakthroughs.
That distinction could become increasingly important if capital becomes more selective. Infrastructure with established customers and long-term contracts may have different risk characteristics from speculative investments based on rapidly changing technology assumptions.
“Blackstone’s mid-year investment outlook argues that private markets are well positioned to help address shortages in compute, power and physical infrastructure” –Wealth Training Company
Selective Capital Deployment Could Define the Next Cycle
As more capital enters AI infrastructure, private-market investors may need to become increasingly selective.
Goldman Sachs estimates that hyperscalers could spend more than $5 trillion on AI and data centres by 2030, while private-market financing is expected to play a growing role in meeting those capital requirements. (Goldman Sachs)
The size of the investment requirement creates opportunities, but it does not mean every project will generate attractive returns.
Power availability, construction costs, financing conditions and customer demand can all influence the economics of individual assets.
Schwarzman’s investment strategy has increasingly emphasised areas where Blackstone believes scale and execution capabilities provide an advantage. The firm has invested across data centres, power generation, private credit and AI companies.
This approach reflects a broader principle of selective capital deployment. Rather than treating AI as a single investment category, investors can examine the infrastructure and financing bottlenecks created by the technology.
The resulting opportunities may include assets that provide essential services to the AI ecosystem without depending entirely on the success of any individual AI model or company.
What Comes After the Initial AI Investment Boom?
The next phase of AI investment could look different from the first. Early investment focused heavily on computing capacity and the companies developing large AI models. Increasingly, attention is shifting towards the infrastructure required to sustain that growth.
Blackstone’s mid-year investment outlook argues that private markets are well positioned to help address shortages in compute, power and physical infrastructure. (Blackstone)
That could favour investors capable of committing substantial amounts of capital over long periods.
For Schwarzman and Blackstone, the opportunity is therefore not simply about predicting which technology company will dominate. It is also about identifying the physical assets and financing structures required regardless of which individual companies ultimately emerge as long-term winners.
At the same time, valuations remain critical. High demand does not automatically guarantee high returns, particularly if too much capital competes for the same assets.
The next stage of the AI investment cycle may consequently reward investors who combine technological understanding with traditional private-market disciplines such as underwriting, asset selection, operational expertise and careful capital deployment.